Is This the Bottom of the Market? BMO Economist Shares What’s Next for Canadian Real Estate
The Bank of Canada and the U.S. Federal Reserve cut rates, sparking fresh debate about whether Canada's housing market has hit bottom. A BMO economist shares what's next.
 Gary McGowanREALTOR® and national real estate trainer
The Bank of Canada and the U.S. Federal Reserve recently announced interest rate cuts, sparking fresh debates about whether Canada’s housing market has finally reached the bottom. While lower borrowing costs bring relief for homeowners and buyers, they also reflect broader economic challenges.
To make sense of it all, let’s dive into the latest BMO Capital Markets presentation, paired with insights from mortgage expert Dion Beg, who’s been advising clients on how to navigate these shifting conditions.
Canada’s Economy: Weak Growth, Rising Unemployment
According to BMO’s Senior Economist Sal Guatieri, Canada’s economy contracted in Q2 of 2025 due to plunging exports and weak business investment. Job losses have mounted across multiple industries, pushing the unemployment rate to a post-pandemic high of 7.1%.
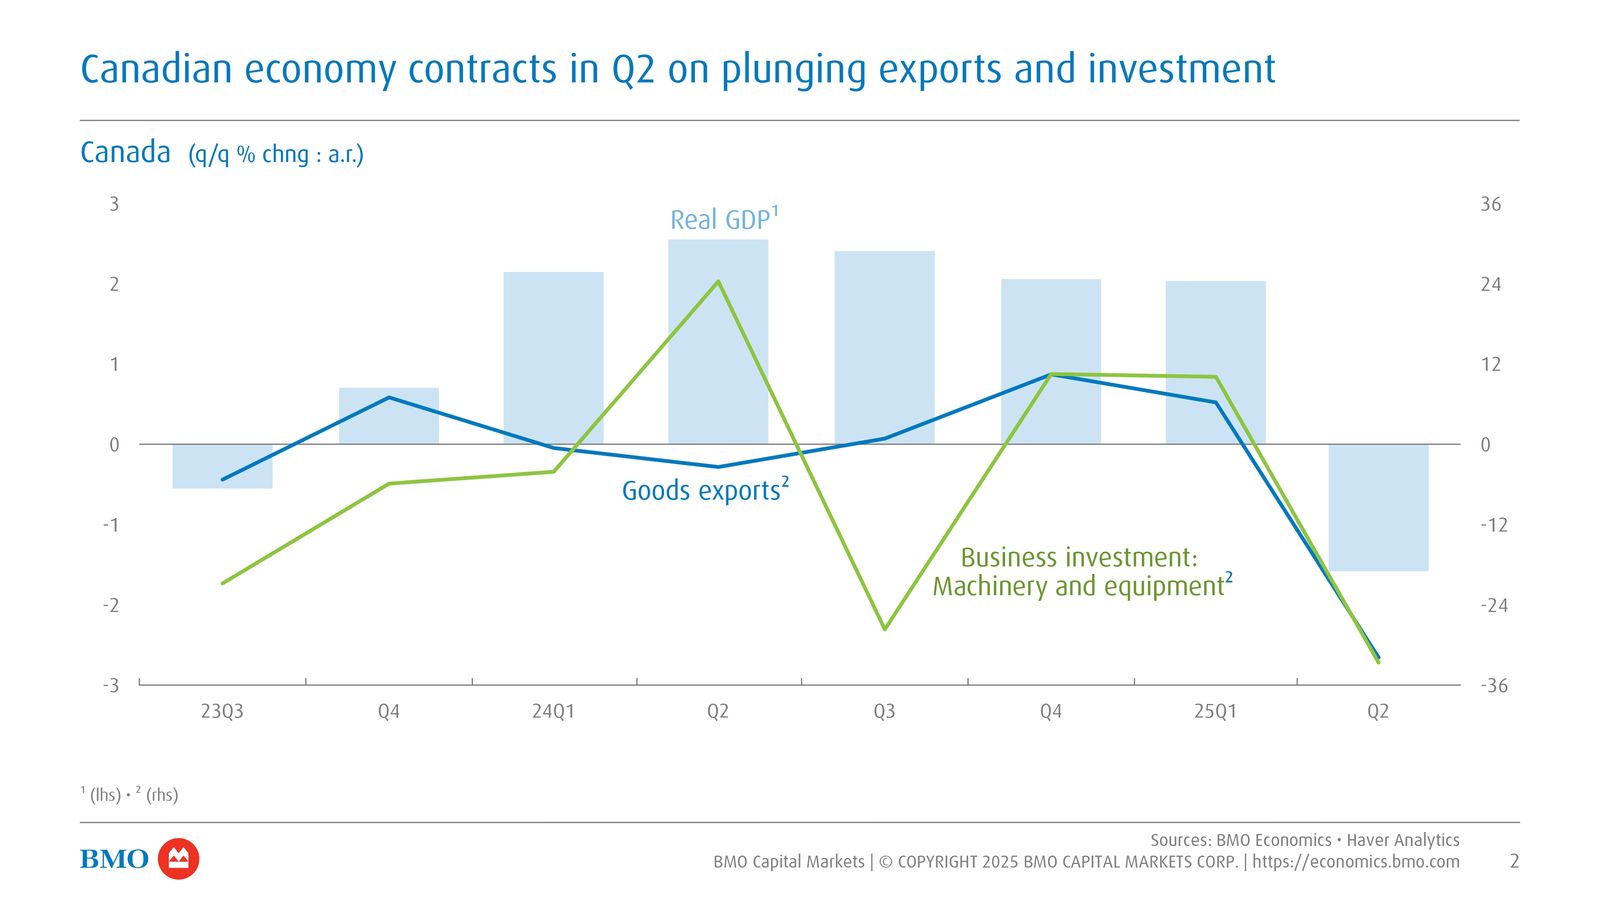
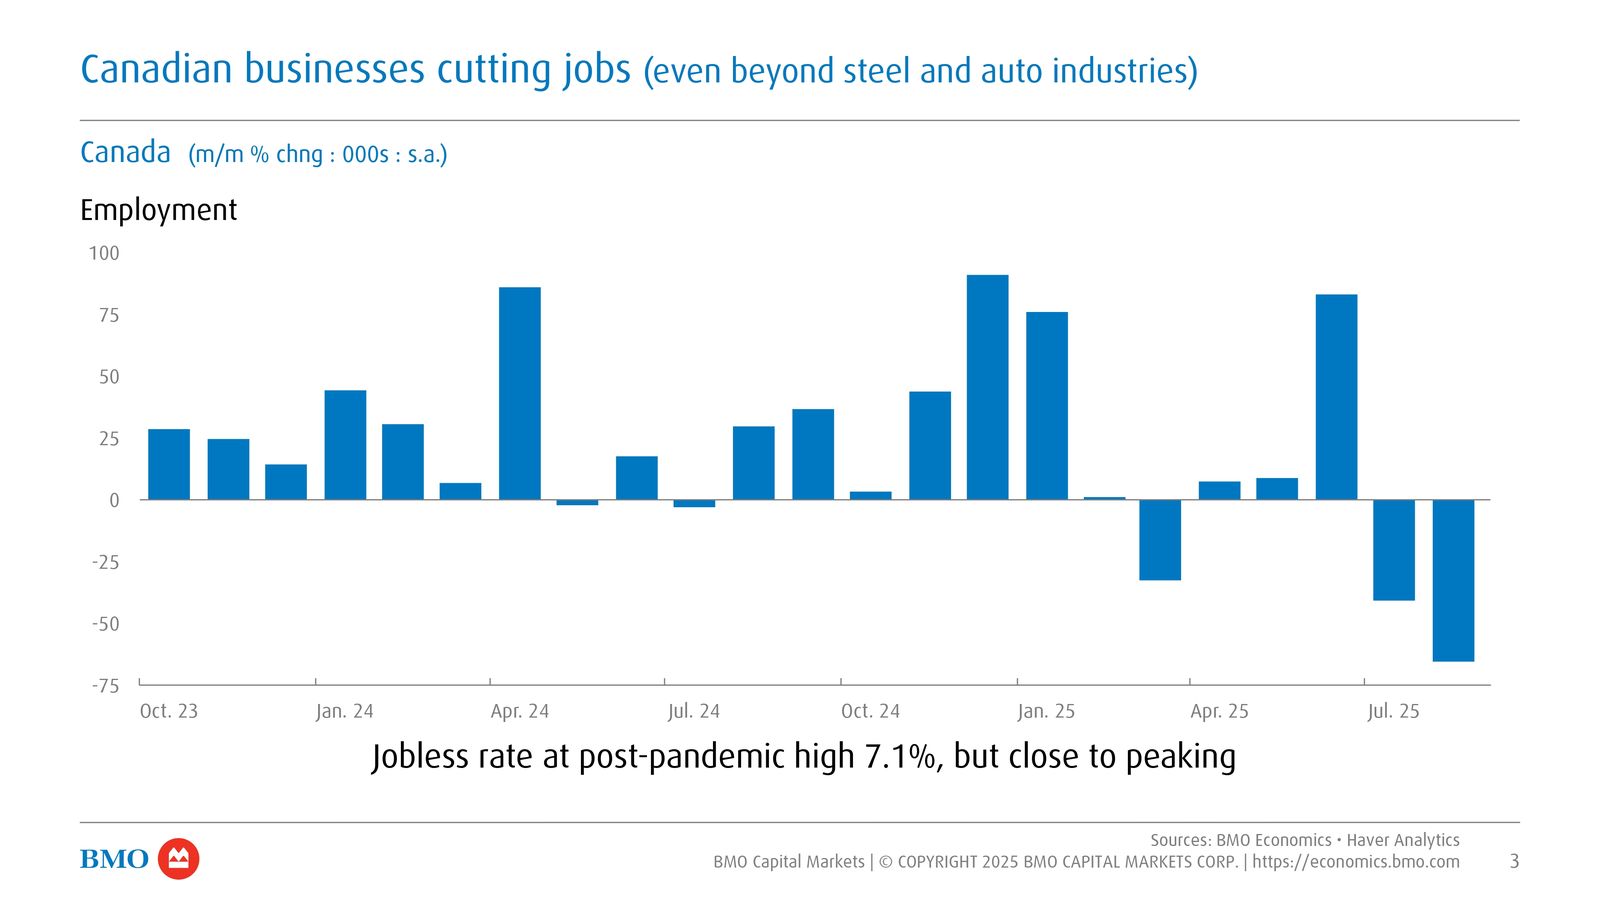
While this is concerning, BMO believes the economy may avoid a full-blown recession thanks to stimulative fiscal policy, low interest rates, and a weaker Canadian dollar boosting exports.
Bank of Canada Rate Outlook
The Bank of Canada has already trimmed its policy rate, with BMO forecasting further declines into 2026. Their outlook suggests:
• End of 2025: Overnight rate at 2.25% (down from 2.75% today)
• End of 2026: Overnight rate at 2.00%
• Longer-term bond yields, however, are expected to decline only modestly
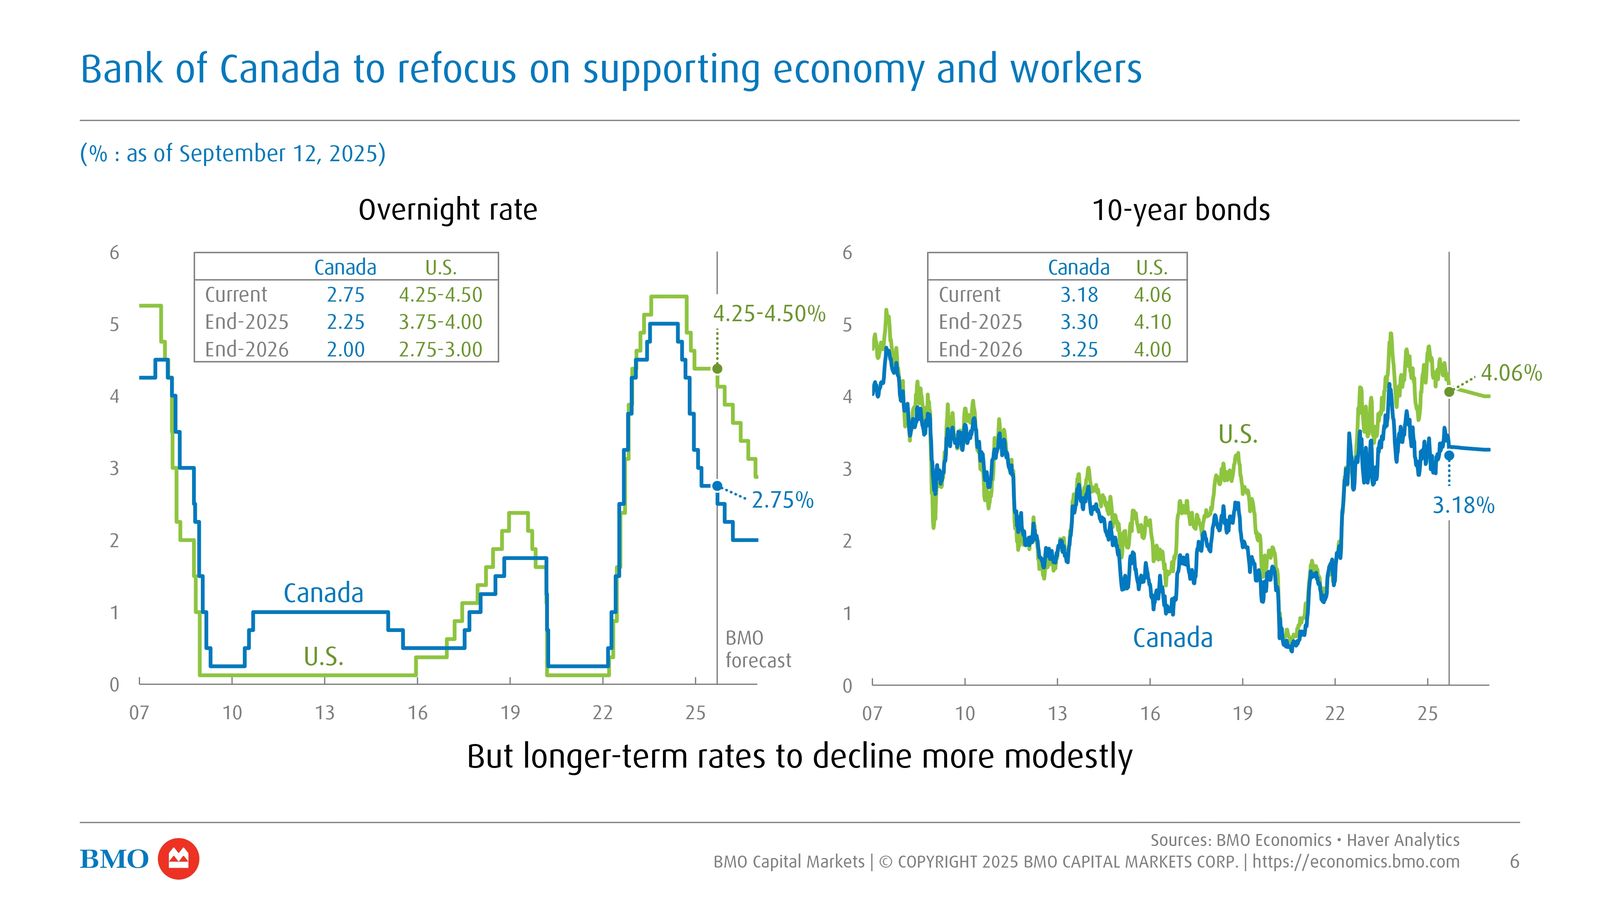
For borrowers, this means variable-rate mortgages could continue to drop, providing meaningful monthly savings. But as Dion Beg reminds his clients, the decision between fixed and variable depends on household income stability and long-term financial planning.
Housing Market: Have We Hit Bottom?
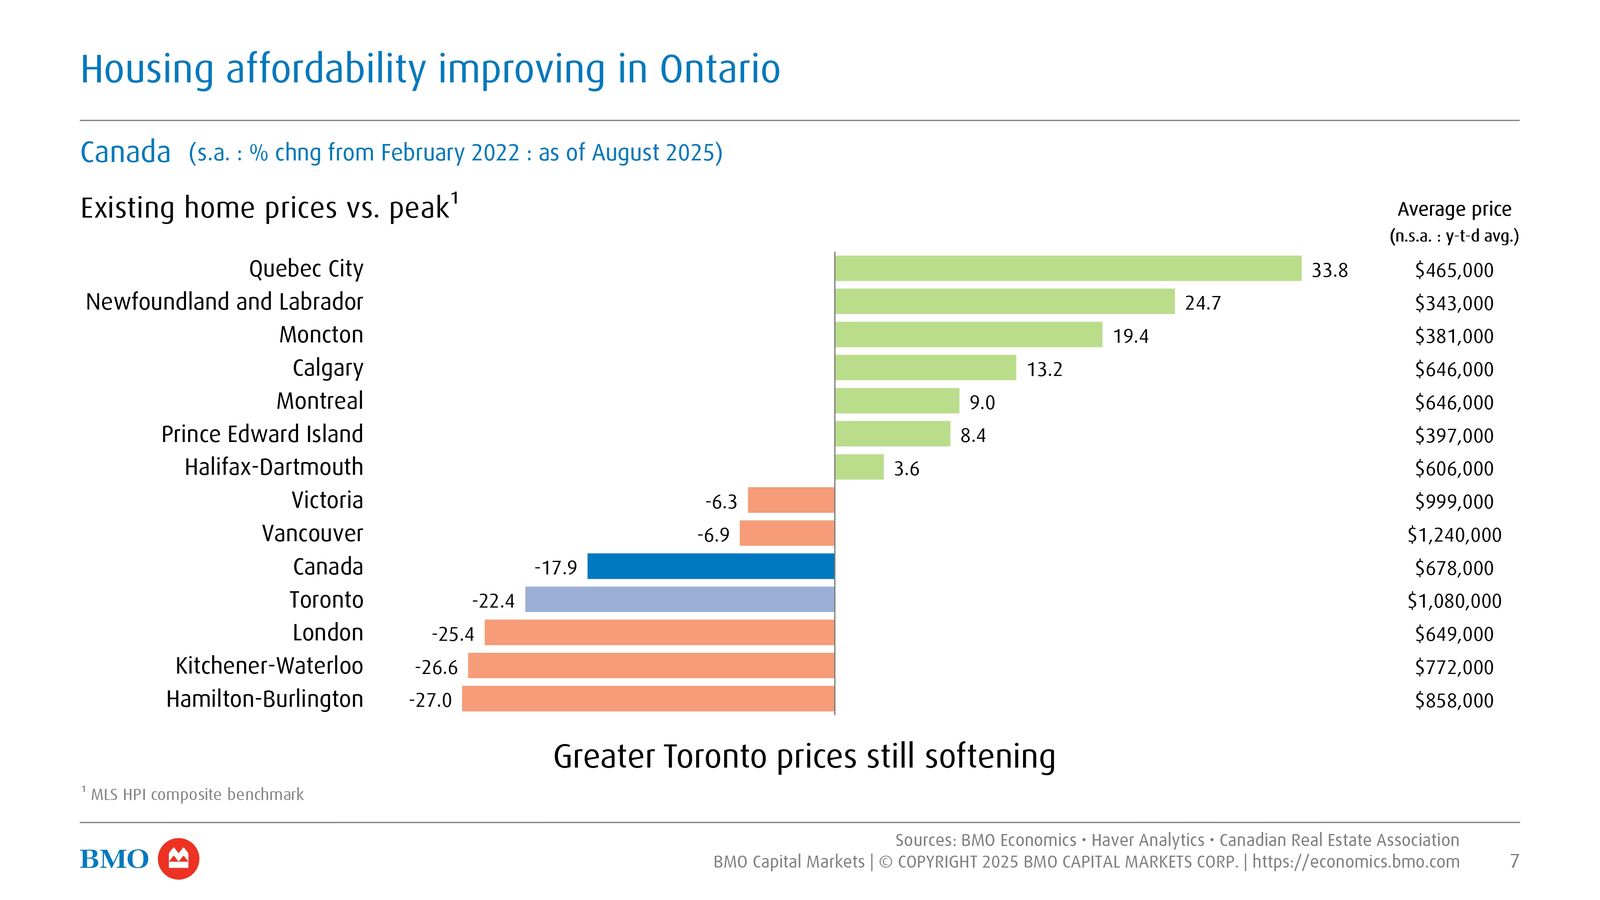
BMO’s data shows existing home prices in Canada remain well below their 2022 peak. In the Greater Toronto Area, prices are still softening, while affordability has started to improve in parts of Ontario.
The big takeaway:
• Nationally: Some markets (Toronto, Vancouver, Hamilton) remain stretched.
• Regionally: Affordability in cities like Quebec City, Moncton, and Calgary looks much healthier.
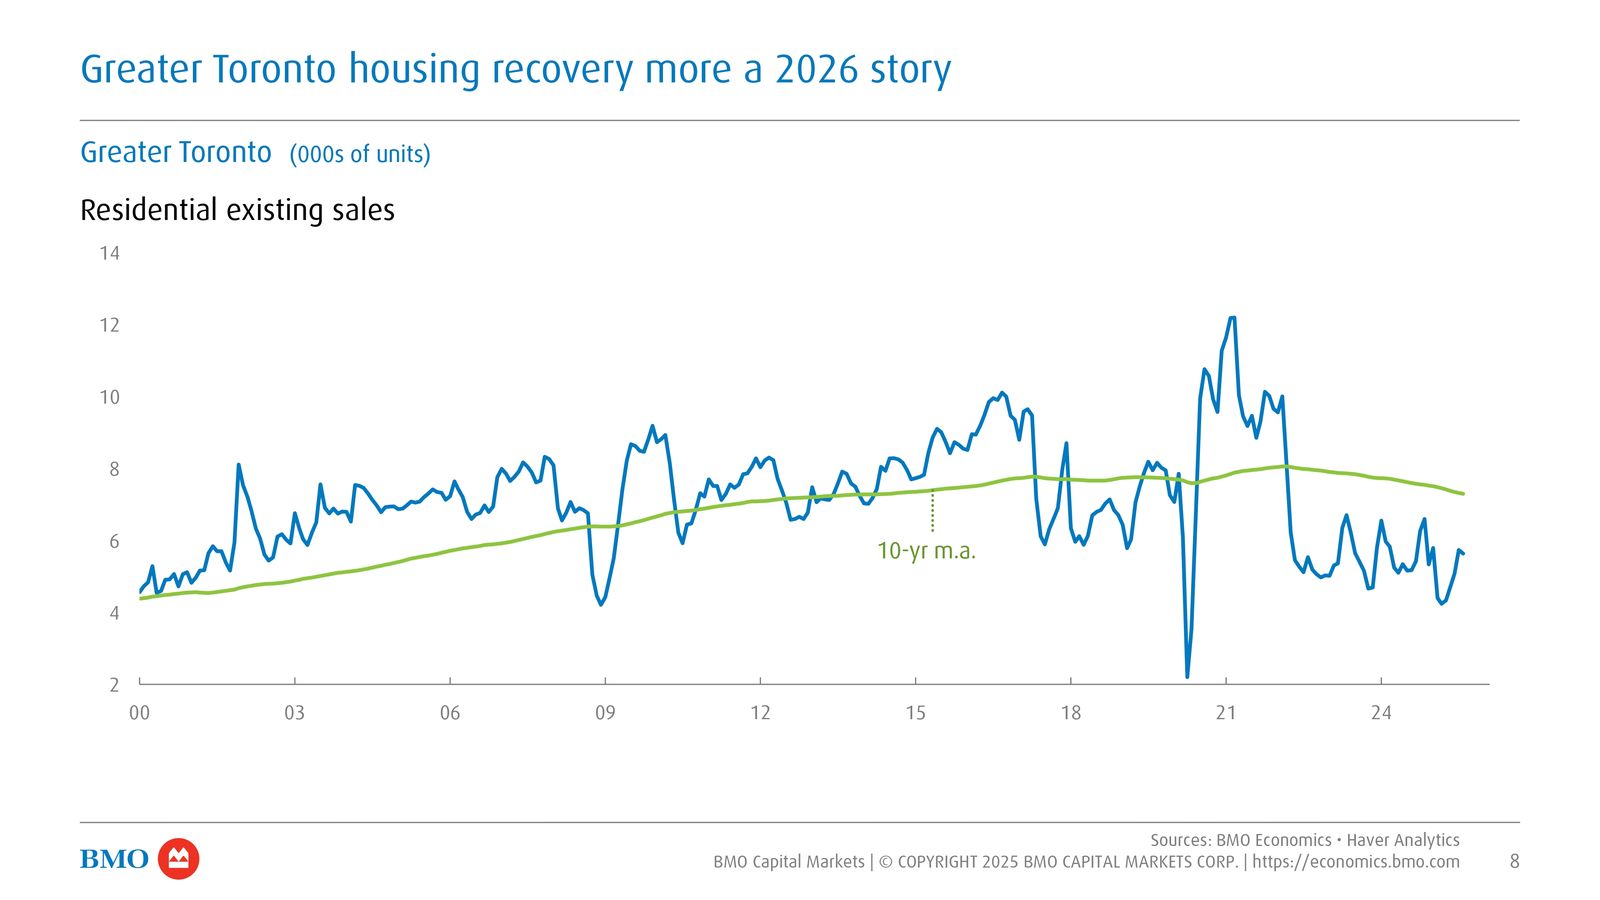
• Timeline: A true housing recovery in the GTA may not arrive until 2026.
What This Means for Buyers and Homeowners
Dion Beg has seen first-hand how these shifts play out. Recent clients include first-time buyers confidently entering the market, some locking in fixed rates for stability, others opting for variable rates to take advantage of potential cuts.
For homeowners, refinancing opportunities are emerging. Some clients are saving $800+ per month by restructuring their mortgages — either putting the cash toward prepayments to pay down debt faster or reallocating it into investments and retirement savings.
Wrap Up
So, is this the bottom of the market?
BMO believes we’re close, with prices stabilizing and affordability gradually improving. But they caution that recovery will be slow, especially in Ontario’s largest markets.
For buyers and investors, this could be a window of opportunity — but it’s crucial to make decisions based on your personal financial situation, job security, and long-term goals.
As Dion Beg says: “It’s not just about getting a mortgage, it’s about making the right mortgage decision for your future.”